business
India’s New Inflation Loop: Oil, Rupee and Rates
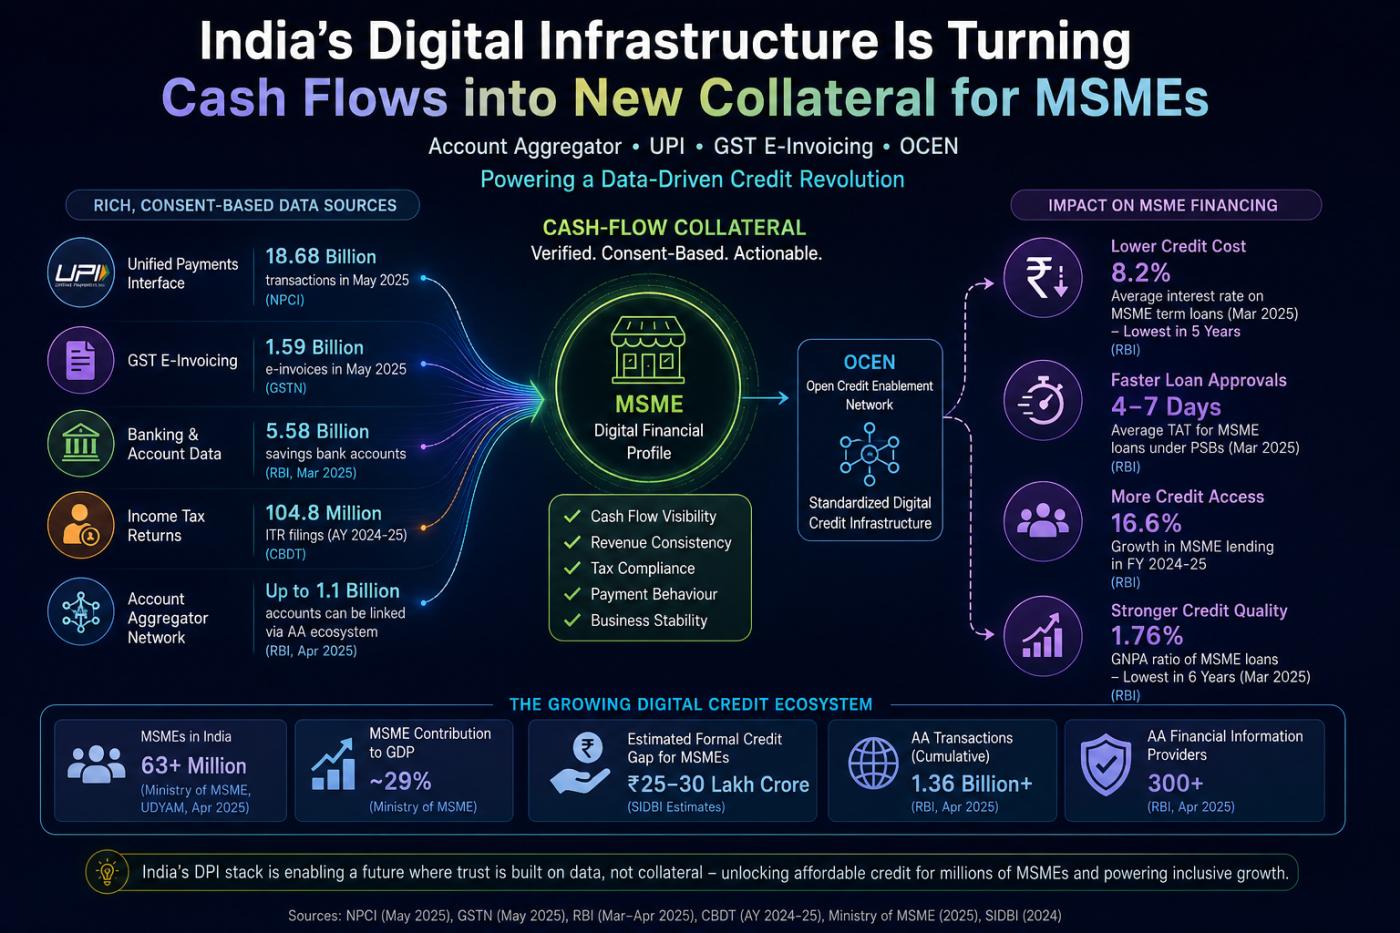
The RBI’s October 2026 rate hike could create a three-way squeeze for import-dependent Indian businesses as crude prices, rupee weakness and financing costs interact. This analysis examines how imported input costs can move through corporate margins, inventories, pricing behaviour and working-capital borrowing, using official RBI, Ministry of Commerce and PPAC data.



The Reserve Bank of India’s October policy decision is easy to describe as a conventional inflation-fighting move: the repo rate was raised by 25 basis points to 5.50%, while the Monetary Policy Committee shifted its stance from neutral to calibrated tightening. But that framing misses a more important business story. India is entering this tightening cycle while facing a combination of higher international energy prices, a weaker rupee, a widening merchandise trade deficit and substantial dependence on imported inputs.
That creates a three-stage pressure mechanism for Indian companies. First, the dollar cost of imported commodities and components rises. Second, rupee depreciation magnifies that increase in domestic-currency terms. Third, the RBI responds to the risk that an initially external supply shock becomes embedded in domestic prices, while higher interest rates simultaneously increase the financing cost of carrying those more expensive inventories.
The result is potentially more complicated than the familiar story of a rate hike making loans more expensive. For import-dependent businesses, the same shock can hit the income statement through input costs and the balance sheet through working-capital requirements before the higher policy rate has much effect on the original source of inflation.
The RBI is tightening against a supply shock, not simply overheating demand
The October 7 monetary policy statement makes the unusual nature of the decision unusually clear. The MPC said CPI inflation had risen to 4.8% in August from 4.5% in July, while core inflation increased to 4.2%. More importantly, the RBI expects CPI inflation to average 5.2% in 2026-27, with inflation projected at 6.0% in the third quarter and 5.7% in the fourth quarter.
The central bank's assessment is significant because it does not describe the inflation problem primarily as excessive domestic demand. It points instead to deficient monsoon conditions, El Niño, food-price pressures and volatility in international oil prices. At the same time, the RBI is increasingly concerned that the initial supply shock could spread into broader pricing behaviour.
Governor Sanjay Malhotra put the monetary-policy dilemma directly: “As regards supply side inflation, monetary policy primarily acts by curtailing second round effects.” That distinction is central to understanding what happens next. A higher repo rate cannot produce more crude oil, repair a disrupted supply chain or strengthen the rupee mechanically. Its purpose is to reduce the probability that businesses and households turn a temporary external shock into persistent domestic inflation.
The RBI also acknowledged the difficulty of separating those effects. Energy and other imported inputs directly raise production costs, while expectations about future prices can cause firms to change pricing behaviour. Those two processes can look similar in inflation data even though they require different economic responses.
The RBI's October 7 Monetary Policy Statement therefore provides a more nuanced explanation than the standard interpretation of the rate decision: monetary policy is being used partly as insurance against second-round effects from an external cost shock.
Why the rupee makes the oil problem more powerful
For an Indian importer, the relevant price of crude, machinery, chemicals or electronic components is not simply the international dollar price. It is the dollar price multiplied by the rupee-dollar exchange rate.
That distinction becomes important in the current environment. The RBI's published reference rates showed the rupee at ₹96.7733 per US dollar at 1 p.m. on October 8. In June, the corresponding RBI-published rate was around ₹94.35 per dollar. The difference may appear modest when expressed as a percentage, but it becomes significant when applied to billions of dollars of imports.
For example, a company importing US$100 million worth of material would face an additional rupee cost of roughly ₹242 crore if the exchange rate moved from ₹94.35 to ₹96.77, even before any change in the dollar price of the material. If the commodity itself becomes more expensive at the same time, the two effects compound rather than merely add to one another.
This is particularly important for industries where imported inputs represent a large share of the cost base. A manufacturer can protect itself against higher commodity prices with long-term contracts or inventory, but that protection becomes less complete when the domestic currency is simultaneously weakening. Similarly, a company that hedges its dollar exposure may reduce exchange-rate uncertainty without eliminating the underlying increase in the cost of the imported commodity.
Crude oil is the obvious transmission channel but not the only one
India's exposure to imported energy remains unusually large. Petroleum Planning & Analysis Cell data show that crude-oil import dependence has been above 88% of petroleum consumption in recent years. In its August 2024 snapshot, PPAC reported crude-oil import dependency of 88.1% for April-August 2024-25, compared with 87.8% a year earlier.
The more recent PPAC data show the scale of the underlying market. During April-August 2024-25, crude imports were 101.6 million tonnes, worth approximately US$60.6 billion, while gross petroleum imports including petroleum products were about US$70.6 billion. Petroleum imports accounted for 24.6% of India's gross imports during that period.
The structural point remains relevant even as the absolute figures change: India does not need to import every finished petroleum product to remain highly exposed to international energy prices. Refiners can import crude, process it domestically and sell fuel into the Indian market. Consequently, an international crude shock can propagate through transportation, chemicals, plastics, packaging, aviation, logistics and manufacturing even when the immediate importer is an oil company.
PPAC's current information also shows how closely the domestic market remains connected to international energy conditions. The agency was publishing an Indian Crude Basket ratio for October 2026 while Delhi petrol and diesel prices were ₹102.12 and ₹95.20 per litre respectively as of October 6.
The Petroleum Planning & Analysis Cell's oil and gas data are therefore useful for looking beyond the headline crude price. They show the physical quantities imported, the value of those imports and the degree of structural dependence behind India's exposure.
The less obvious problem: electronics and capital goods
Oil is only one side of the current external-sector problem. The RBI's October statement notes that India's merchandise trade deficit widened to US$58.7 billion in July-August 2026 from US$55.1 billion a year earlier, with the increase driven mainly by electronic-goods and crude-oil imports.
This combination is particularly interesting because the two categories affect the economy differently. Crude is a classic commodity input whose price can feed into transportation and production costs. Electronic goods, by contrast, represent India's dependence on imported manufactured components and finished products, particularly within increasingly complex supply chains.
The RBI also noted that imports of capital goods rose 24.5% year-on-year during July-August 2026, while IIP capital-goods production increased 17.9%. That suggests an economy still investing aggressively even as external costs rise.
This creates an underappreciated interest-rate channel. A manufacturer importing machinery or electronic components may experience a higher landed cost because of currency movements, but it may also need more rupee financing to maintain the same level of inventory. If its bank simultaneously raises lending rates, the company faces both a higher numerator and a higher financing cost.
Consider a distributor that normally carries ₹100 crore of imported inventory. A 5% increase in its rupee-denominated replacement cost raises the inventory requirement by ₹5 crore. If that additional working capital is borrowed, the company pays interest on the higher inventory value as well. A rate hike therefore does not simply increase the cost of existing debt; it can increase the amount of debt required to finance a given physical volume of goods.
That is where the repo rate meets corporate margins
The distinction matters most for businesses with long inventory cycles, thin operating margins or weak pricing power.
Suppose an importer buys a component for US$1 million. At ₹94.35 per dollar, the purchase costs roughly ₹9.44 crore. At ₹96.77, it costs approximately ₹9.68 crore an increase of around ₹24 lakh without any change in the foreign supplier's price.
If the importer cannot immediately pass that increase to customers, the margin absorbs the currency shock. If it decides to preserve its margin by raising selling prices, it contributes to the second-round inflation process that the RBI is explicitly monitoring. If it finances its inventory with floating-rate borrowing, the higher policy rate then adds another cost.
This produces a feedback loop:
higher global commodity/input prices → larger dollar import bill → rupee cost inflation → pressure on corporate margins → higher selling prices → broader inflation expectations → tighter RBI policy → higher working-capital costs.
The important insight is that the last step does not reverse the first one. Higher interest rates cannot make imported crude cheaper. They can, however, make it harder for businesses to finance inventories and easier for weaker demand to eventually force companies to absorb rather than pass through some of the higher costs.
Why the RBI is watching corporate pricing behaviour
This is precisely why the RBI's language about “second round effects” deserves more attention from businesses than the 25-basis-point number itself.
The October statement says that the share of CPI items recording inflation above 4% had risen to about 37% in August. Core inflation had reached 4.2%. Those indicators matter because a central bank becomes more concerned when an energy or food shock begins appearing across unrelated categories.
Governor Malhotra's statement also makes clear that the central bank is not claiming that monetary policy can eliminate supply-side inflation. Rather, it is trying to prevent the shock from becoming self-reinforcing through expectations, wages, pricing decisions and credit demand.
For companies, that creates an unusual strategic tension. Raising prices protects margins but may weaken demand and contribute to inflation persistence. Holding prices protects market share but transfers the shock into margins. Cutting inventories reduces financing requirements but increases the risk of stock-outs and lost sales if replacement costs rise rapidly.
Large companies with sophisticated treasury operations can partly manage this problem through currency hedging, commodity contracts, diversified suppliers and longer-term financing. Smaller import-dependent firms are much more exposed because their working capital is often bank-funded and their ability to hedge foreign exchange or commodity prices is limited.
Liquidity could matter as much as the 25-basis-point hike
There is another reason the headline repo-rate increase should not be viewed in isolation. The RBI reported that system liquidity had averaged a surplus of ₹5.9 lakh crore since the August policy meeting. It also said that commercial-paper and certificate-of-deposit rates had moderated significantly during August and September.
That means the immediate transmission of the rate hike will depend partly on how the RBI manages liquidity. The central bank explicitly said it would use an appropriate mix of liquidity-management tools and seek to align the weighted average call rate with the policy repo rate.
This distinction is important for corporate borrowers. A 25-basis-point increase in the policy rate is a benchmark change; the actual cost paid by a company depends on the bank's marginal funding cost, the company's credit risk, the lending benchmark used, the maturity of its borrowing and prevailing money-market conditions.
In other words, businesses should watch the transmission data rather than simply multiply their debt by 0.25%. The eventual effect could be smaller, larger or slower depending on deposit repricing, bank competition, liquidity conditions and credit demand.
The external sector makes the timing especially important
The RBI's own external-sector assessment provides another reason for caution. India's merchandise trade deficit rose to US$58.7 billion in July-August 2026, while net FDI inflows during April-August were US$13.8 billion, up from US$9.6 billion a year earlier. At the same time, the RBI reported net FPI outflows of US$10.3 billion through October 5.
India therefore enters the tightening phase with strong domestic growth but an external environment that is less forgiving. Real GDP grew 7.8% in the first quarter of 2026-27, and the RBI raised its full-year growth forecast to 7.1%. Yet higher energy prices, global bond yields, trade uncertainty and capital-flow volatility create a difficult combination for the rupee and for companies dependent on imported inputs.
The policy challenge is consequently asymmetric. If the RBI does too little, imported inflation may become embedded in domestic pricing. If it tightens too aggressively, companies whose cost shock originated abroad could face weaker demand and more expensive financing without any corresponding reduction in their input costs.
Which businesses face the greatest squeeze?
The most exposed businesses are not necessarily those with the largest debt. A better way to identify vulnerability is to look at the intersection of three variables: imported-input intensity, inventory requirements and pricing power.
Petroleum-linked businesses face direct exposure to crude and energy prices, although refiners and downstream companies can have different degrees of pass-through and hedging protection.
Chemical manufacturers can face simultaneous exposure to crude-derived feedstocks, imported chemicals and energy-intensive production. Currency depreciation can therefore amplify an already volatile input-cost environment.
Electronics and component manufacturers face a different problem: their exposure is often embedded in imported components and intermediate goods rather than a single commodity. Currency weakness can raise the replacement cost of inventory quickly.
Machinery and capital-goods companies may be less immediately vulnerable to consumer inflation but can face a financing squeeze because imported equipment becomes more expensive at exactly the point when interest rates are rising.
Pharmaceutical manufacturers can face currency and imported-input exposure while simultaneously dealing with regulated pricing and competitive constraints, limiting their ability to pass through every increase in cost.
Import-heavy MSMEs may be the most vulnerable of all. Their bargaining power with suppliers and customers is limited, their working-capital cycles can be long, and access to sophisticated foreign-exchange hedging is often weaker than at larger corporations.
The real question for corporate India
The October policy decision should therefore be read less as a simple 25-basis-point increase and more as a warning about the direction of India's inflation-financing environment.
The RBI has effectively drawn a line between an external shock and the domestic behaviour that follows it. Its concern is not that monetary policy can reduce the international price of crude or imported electronics. Its concern is what happens after those costs reach Indian companies: whether firms raise prices, whether households change expectations, whether credit demand remains strong and whether inflation becomes sufficiently broad to persist.
For corporate India, the implication is that currency management, inventory management and financing strategy are becoming interconnected decisions. An importer that focuses only on the dollar price of its inputs may miss the cost of rupee depreciation. A treasury team that hedges currency exposure but ignores working-capital financing may still see margins deteriorate. And a company that protects margins entirely through price increases may eventually encounter weaker demand and contribute to exactly the inflation persistence the RBI is trying to prevent.
The RBI's October decision thus creates an unusual business test: can Indian companies absorb an externally generated cost shock without allowing it to become a domestically financed inflation cycle? The answer will depend not only on the next move in the repo rate, but on the behaviour of the rupee, crude prices, import volumes, corporate pricing and bank credit over the next several quarters.
The Ministry of Commerce and Industry's TradeStat database, which was updated on October 8 and contains monthly import data through August 2026, provides the most useful official framework for tracking which commodity groups are actually driving the import bill. That makes it possible to move beyond the broad claim that “imports are expensive” and identify where India's external cost shock is concentrating and, ultimately, which balance sheets are carrying it.