Fundamentals for Kimberly-Clark Corporation
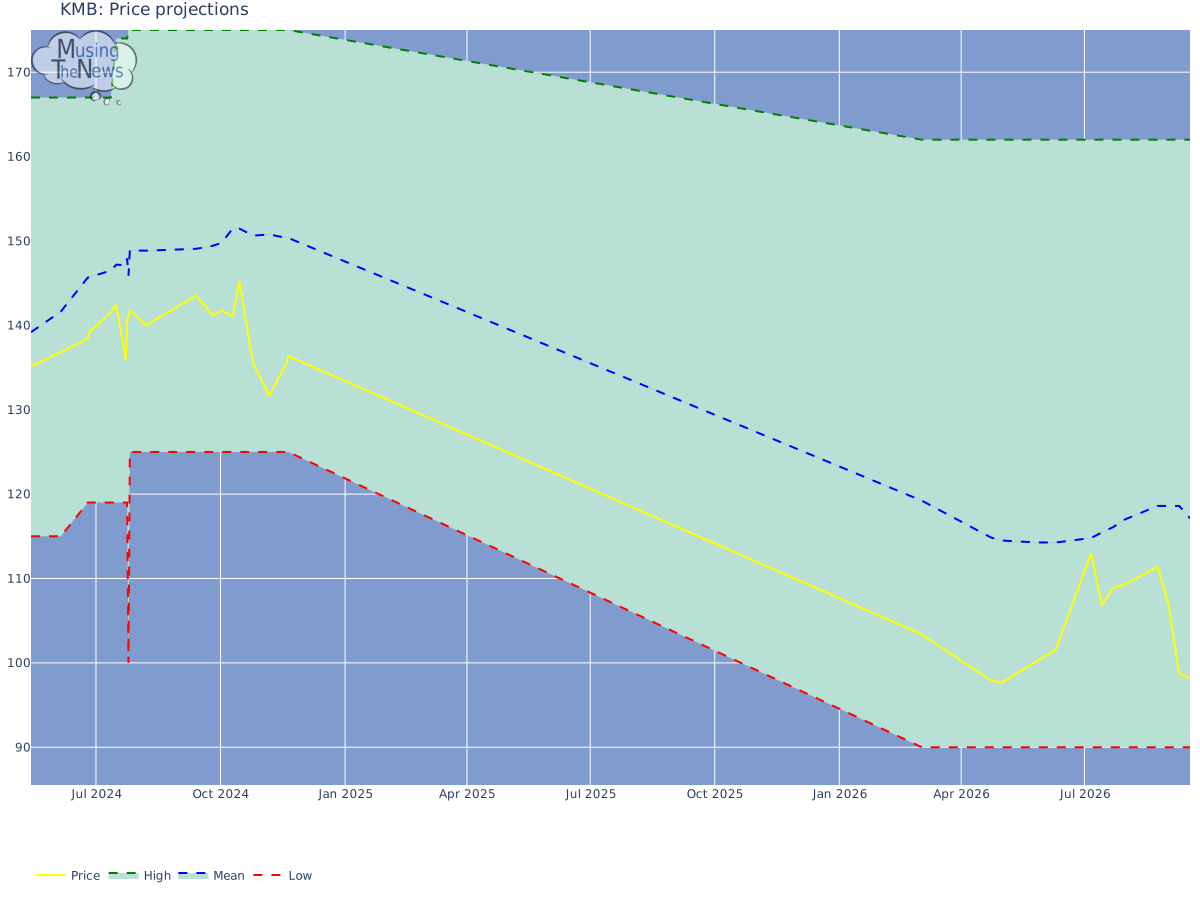
KMB's price projections have been revised downward gradually, indicating that analysts are tempering their expectations. This downward shift suggests a more cautious outloo...




Business Operations:
Sector: Consumer DefensiveIndustry: Household & Personal Products
Kimberly-Clark Corporation, together with its subsidiaries, manufactures and markets personal care products in the United States. It operates in two segments, North America and International Personal Care. The North America segment offers disposable diapers, training and youth pants, swimpants, baby wipes, feminine and incontinence care products, reusable underwear, facial and bathroom tissue, paper towels, napkins, wipers, tissue, towels, soaps and sanitizers, and other related products under the Huggies, Pull-Ups, Goodnites, Kotex, Poise, Depend, Kleenex, Scott, Cottonelle, Viva, Wypall , and other brand names. Its International Personal Care segment provides baby and child care, adult care and feminine care, including disposable diapers, training and youth pants, swimpants, baby wipes, feminine and incontinence care products, reusable underwear, and other related products under the Huggies, Kotex, Goodfeel, Intimus, Depend, and other brand names. The company sells its household use products directly to supermarkets, mass merchandisers, drugstores, warehouse clubs, variety and department stores, and other retail outlets, as well as through other distributors and e-commerce. It also sells its professional use products through distributors, directly to manufacturing, lodging, office building, food service, and high-volume public facilities, and through e-commerce. Kimberly-Clark Corporation was founded in 1872 and is headquartered in Dallas, Texas.
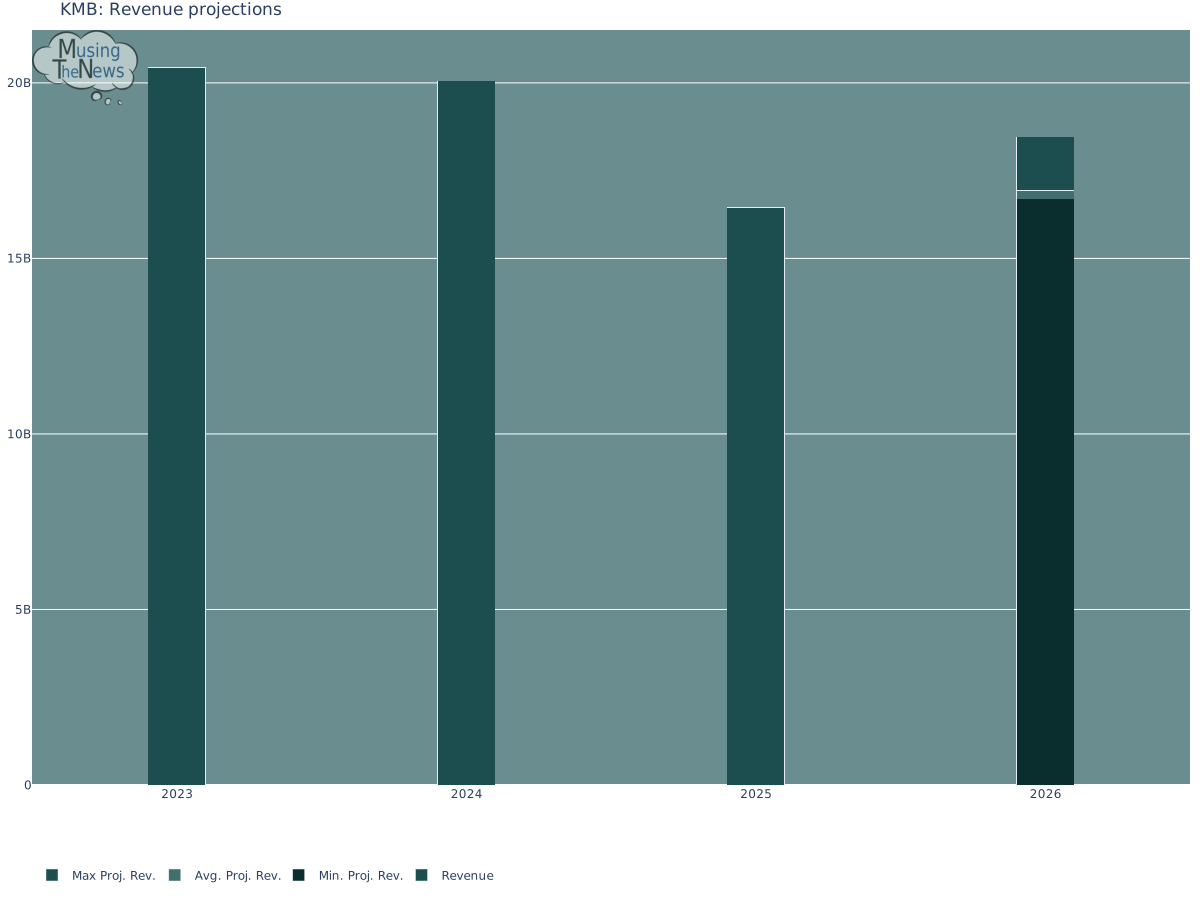
Revenue projections:
Financial Ratios:
| currentRatio | 0.909000 |
|---|---|
| forwardPE | 12.613691 |
| debtToEquity | 348.933000 |
| earningsGrowth | -0.323000 |
| revenueGrowth | 0.006000 |
| grossMargins | 0.376130 |
| operatingMargins | 0.190020 |
| trailingEps | 5.060000 |
| forwardEps | 7.480760 |
With KMB's Forward PE in a favorable range, the stock appears reasonably priced compared to its earnings. This suggests that it's not overpriced and there is room for growth, providing an encouraging opportunity for investors seeking future value increases.
KMB's high debt-to-equity ratio indicates a high level of leverage, meaning the company relies significantly on debt for financing. This can increase financial risk, particularly in times of economic instability or reduced profitability.
Kimberly-Clark Corporation's low earnings and revenue growth point to a likely decrease in profits. This suggests that the company is facing financial difficulties and may struggle to maintain its current level of profitability.
KMB's negative gross and operating margins highlight that the company is incurring losses, unable to generate profit from production or operations. This could be a sign of rising costs or declining revenues, impacting its financial outlook.
KMB's forward EPS being higher than its trailing EPS suggests that the company is expected to generate stronger profits this year. This points to improving financial performance, with KMB anticipated to deliver better earnings than it did in the prior year.
Price projections:
Insider Transactions:
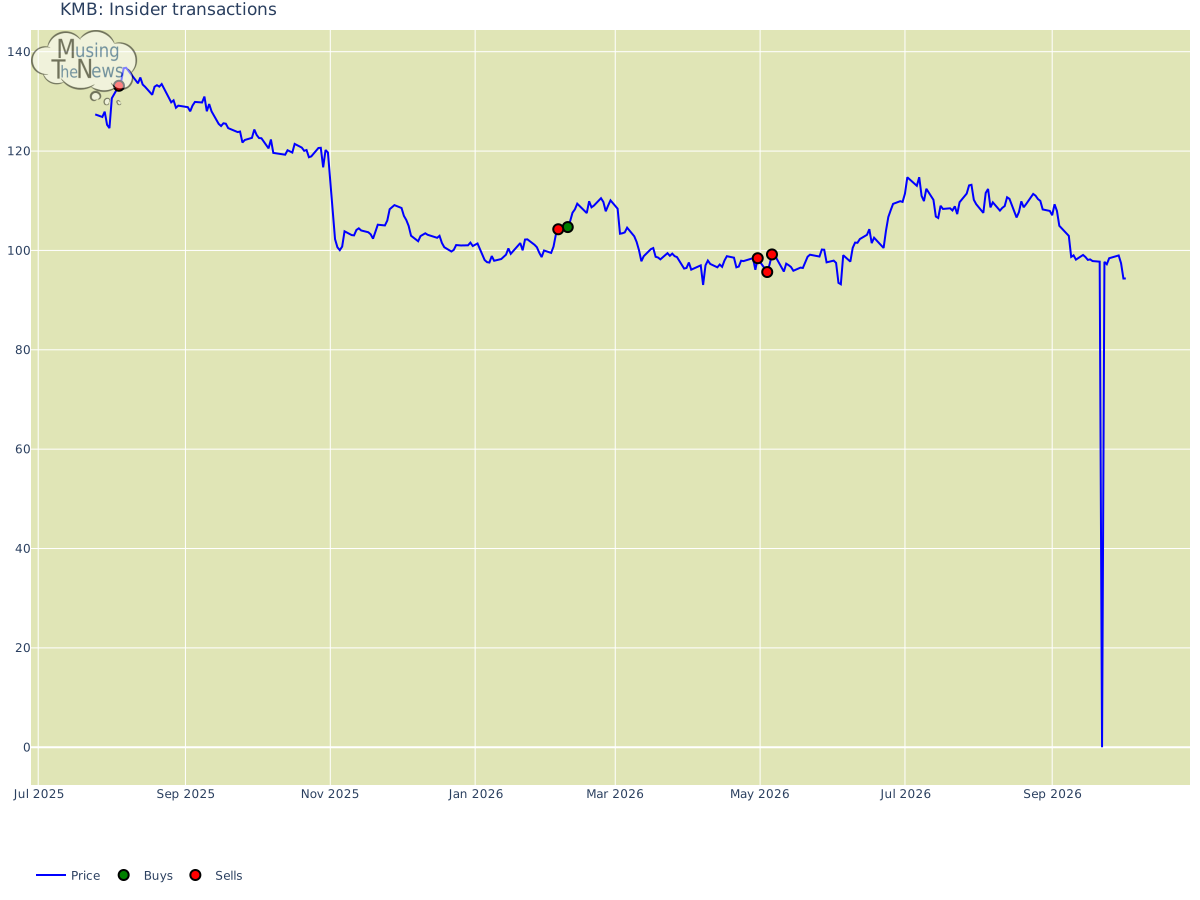
5 transactions to sell KMB occurred, with market price at 106.13400115966797.1 Kimberly-Clark Corporation stock purchases took place, with market price of 104.69999694824219.Insider transactions fail to demonstrate any noticeable trend, leaving ambiguity about the company's potential trajectory or changes in its strategic approach.
Recommendation changes over time:
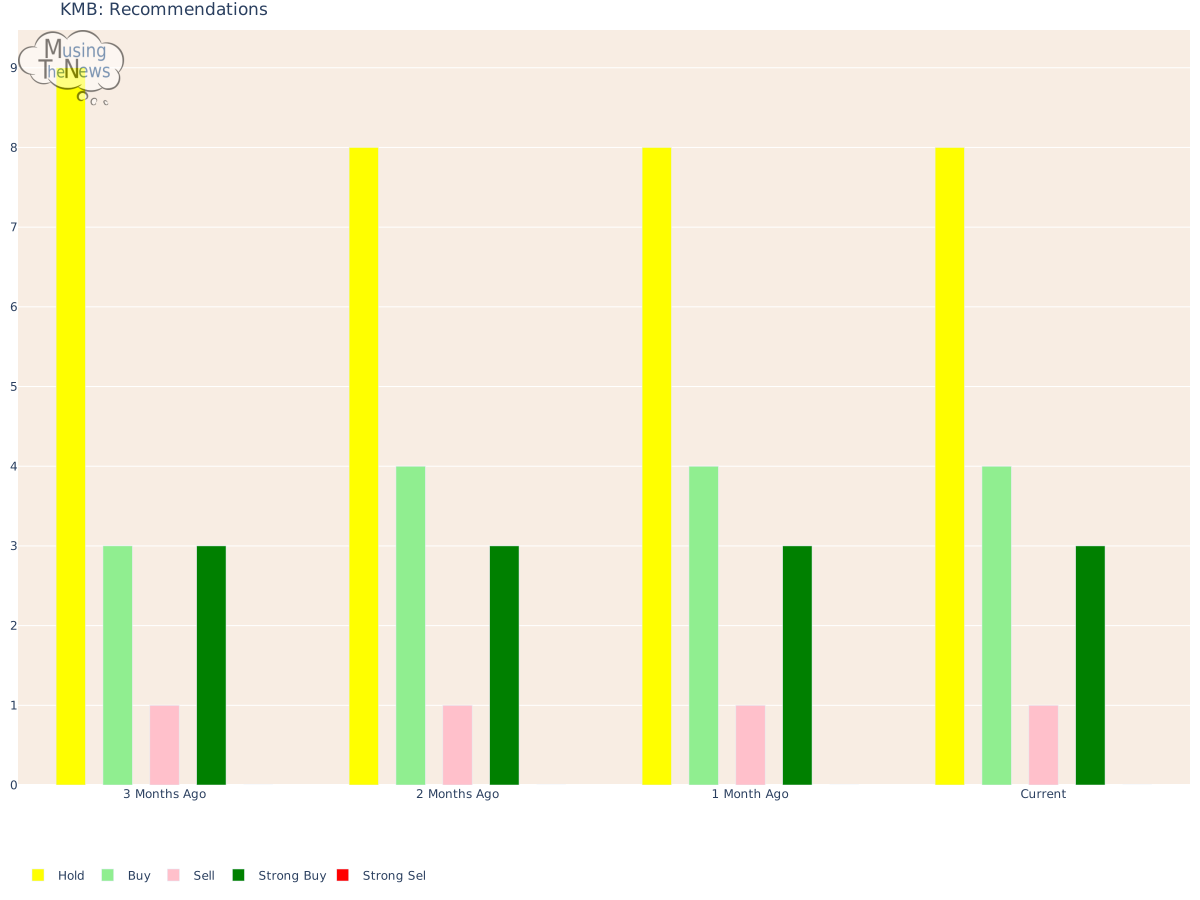
Analysts' recent buy bias toward KMB suggests the stock is gaining favor as a strong investment choice. This optimism could drive more investors to see KMB as a smart place to invest, further bolstering confidence in the company's long-term growth and potential returns.